
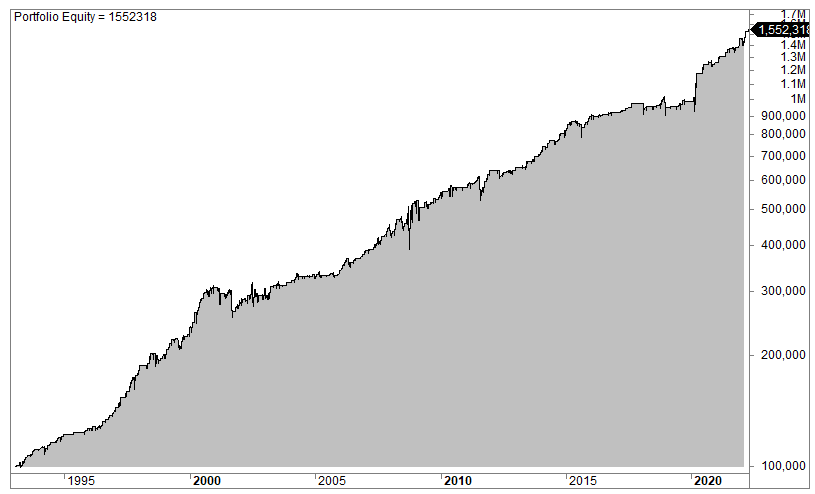
RSI Trading Strategy (91% Win Rate): Statistics, Facts And Historical Backtests!
This article examines how the RSI indicator works and how to develop an RSI trading strategy. The Relative Strength Index (RSI) was developed by Welles Wilder and first introduced in a magazine called Commodities (now Futures) in June 1978. Wilder published a book in the same year called New Concepts In Technical Trading Systems (he also published the ADX indicator in the same book, an indicator we will cover later). The RSI has become one of the most widely used indicators for traders.
Our research indicates that RSI is one of the most useful indicators for trading strategies. However, it works best together with a second indicator or variable. Filters or additional criteria are needed for the RSI to be used in a trading strategy. The indicator works best on securities that are mean-reverting.
(At the bottom of the article, we provide a video with a backtested RSI trading strategy with a win rate of 91%.)
Most websites present the Relative Strength Index by using anecdotal evidence. But you need to backtest to determine if something has any predictive value. In this article, we show you how to use the RSI indicator.
We have backtested trading systems for over 20 years and can confirm that the RSI works reasonably well on stocks and stock indices. As such, the RSI can be used in mean-reverting trading strategies, but only when you add some more criteria, variables, or filters.
If you find this article useful, you might want to have a look at our landing pages for a lot of other trading strategies and edges: